Article
/
My Office Is Waiting at the Gate (Thanks, Chase Sapphire)
My Office Is Waiting at the Gate (Thanks, Chase Sapphire)
My Office Is Waiting at the Gate (Thanks, Chase Sapphire)
My Office Is Waiting at the Gate (Thanks, Chase Sapphire)
My Office Is Waiting at the Gate (Thanks, Chase Sapphire)
Words by
Oveth Martinez
Published on
10.12.2026

For years I spent that time the way most people do. I'd hunt for an outlet, sit on the floor next to it, and pay airport prices for a coffee and a sad breakfast sandwich. Then I got a card that gets me into the Chase Sapphire Lounge, and that dead time turned into some of my most productive hours while I wait for my flight.
Not many people talk about this, at least not photographers, so here's what I use. I'll start with the lounge, then walk through the six cards I carry and the one job each of them has.
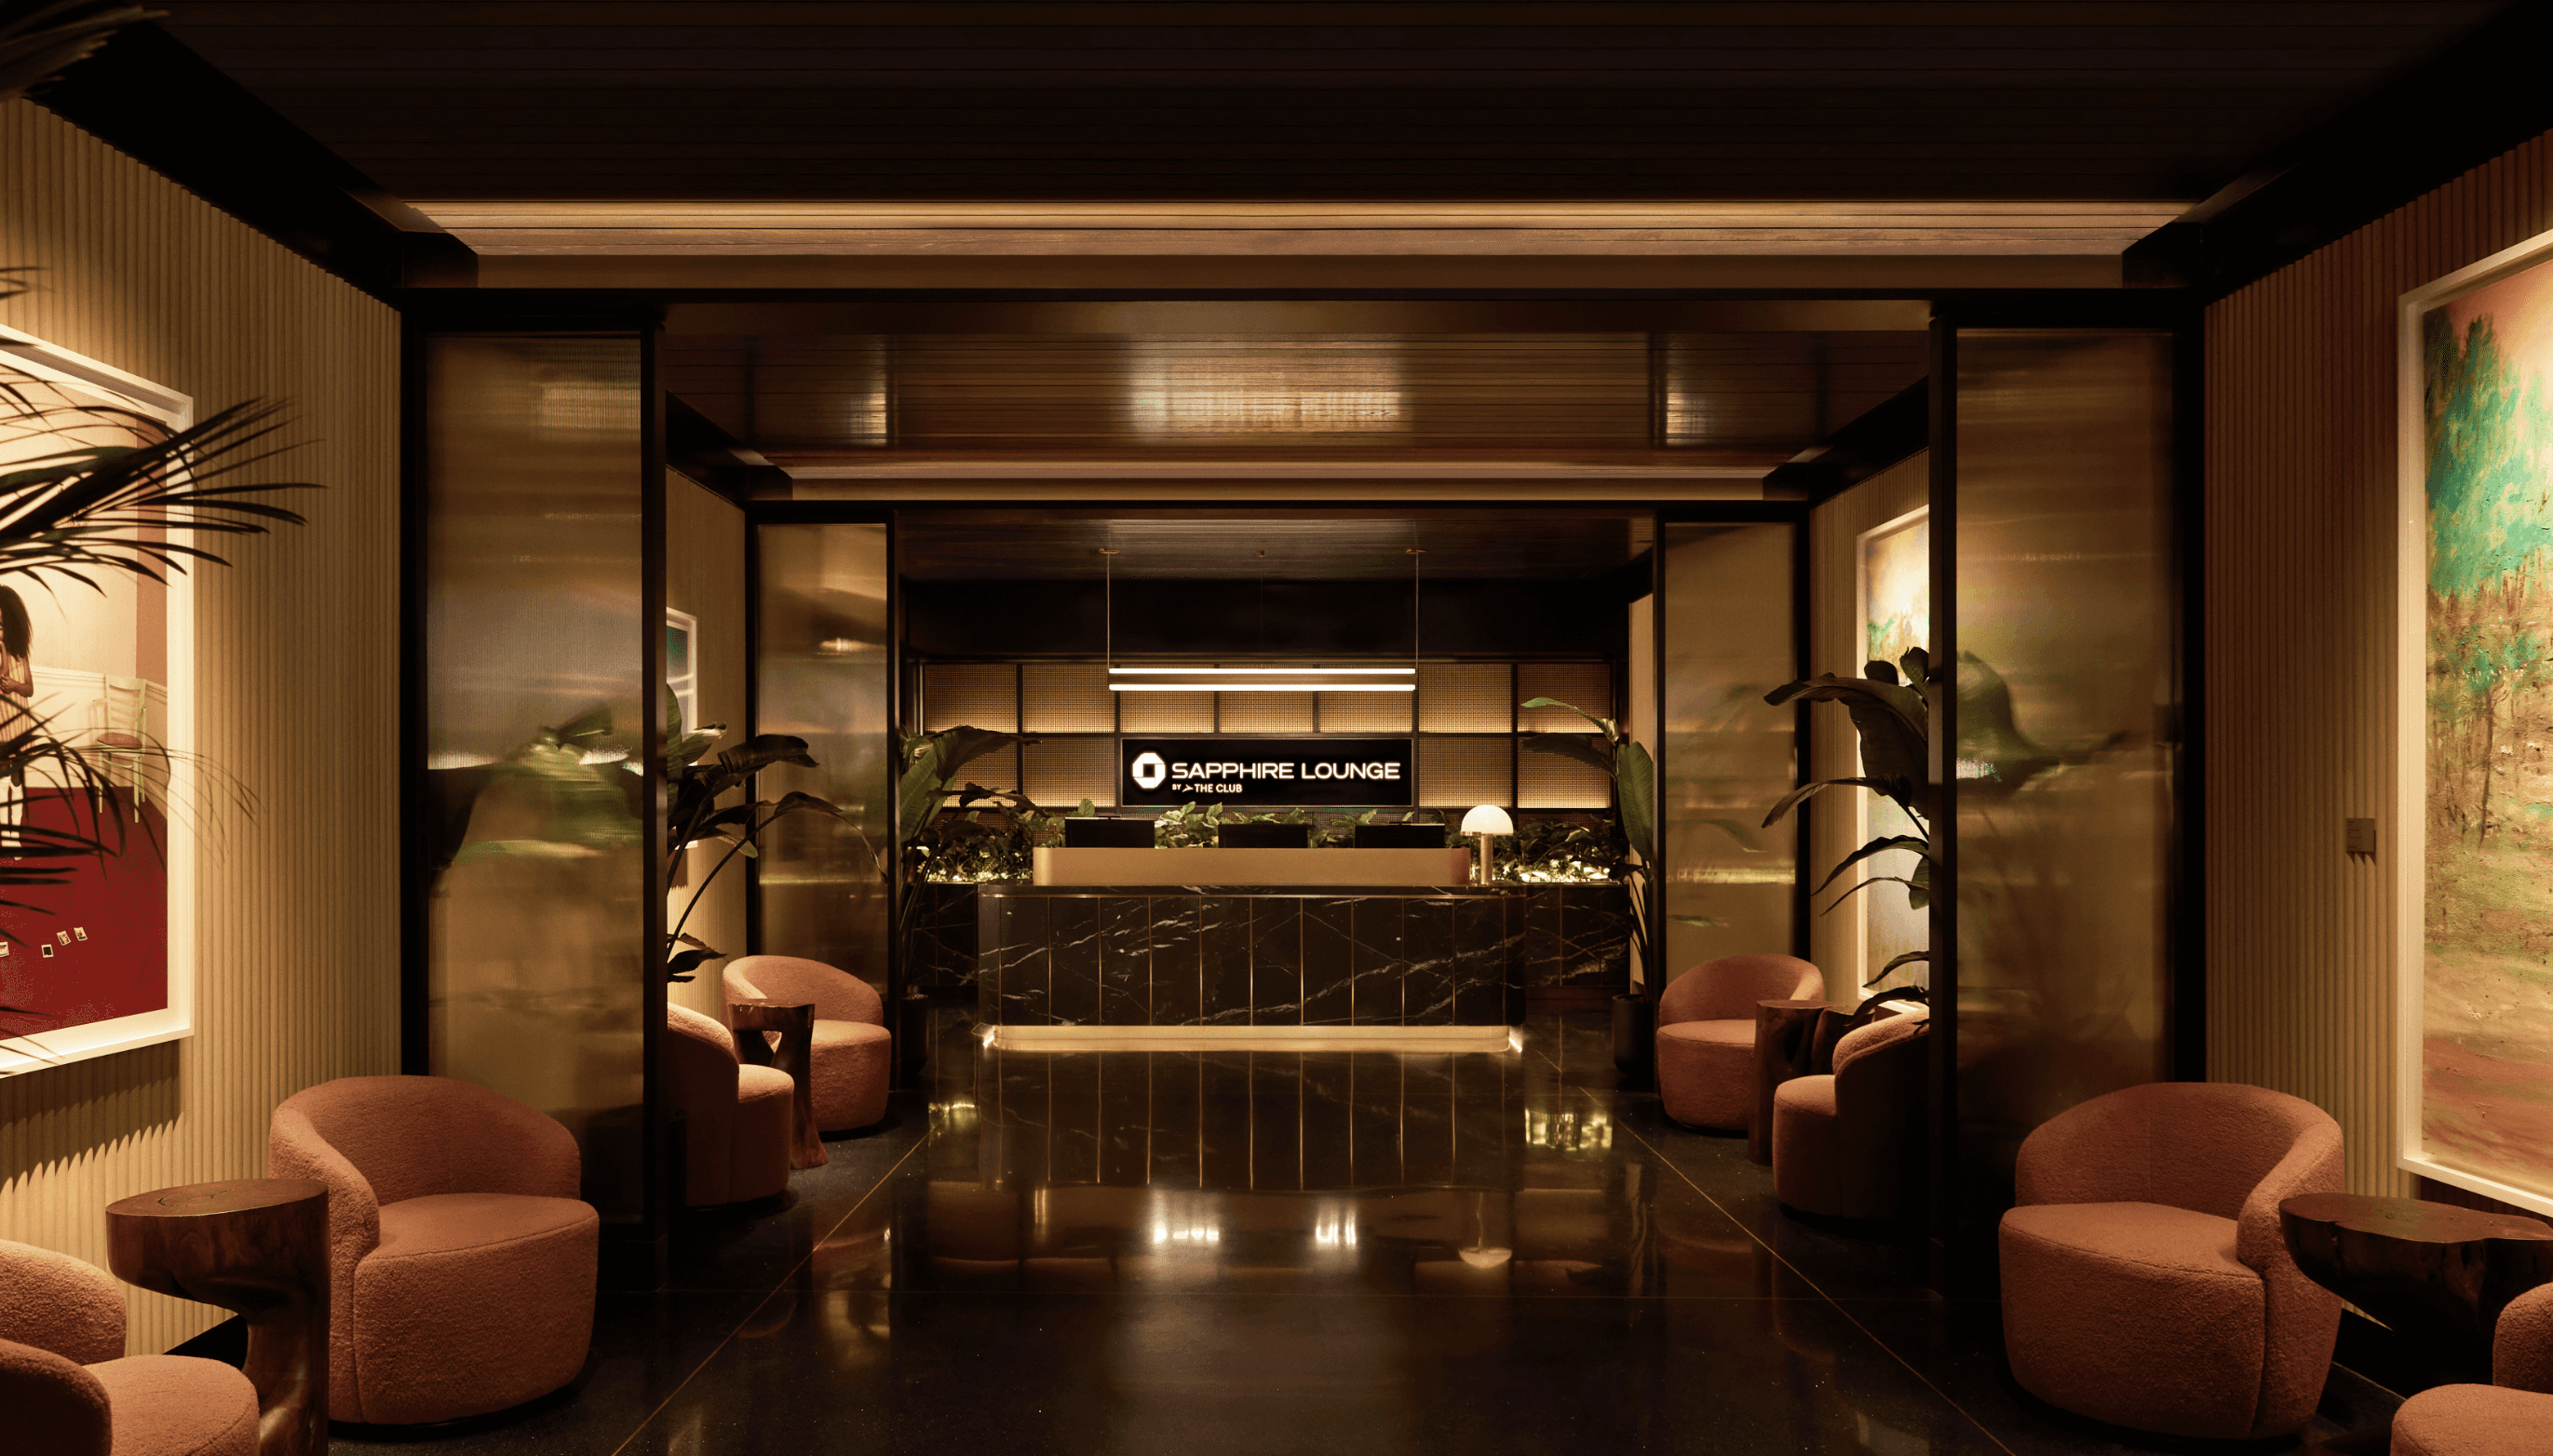
Why the lounge is the best office in the airport
The Sapphire Lounge gives me a real seat, fast Wi-Fi, outlets, and enough quiet to actually think. That's all I need to get work done before a flight.
I use that window to answer client emails, send invoices, cull selects from the last shoot, and go over the shot list for the one I'm flying to. By the time I board, my inbox is handled and I can sleep on the plane without feeling behind.
Then there's the food. Coffee, a proper breakfast, and drinks are all included. At the terminal, a coffee and a basic airport breakfast runs me $30, $40, sometimes $50. Do that on both legs of a trip and you've spent close to $100 before the job has even started. In the lounge it costs nothing extra.
A few things to know before you plan around it:
Sapphire Lounges are open in Boston, Las Vegas, New York (LaGuardia and JFK), Philadelphia, Phoenix, and San Diego. Dallas/Fort Worth and Los Angeles are planned.
You can bring two guests in for free.
The same card comes with a Priority Pass Select membership, which covers 1,300+ other lounges around the world for the airports that don't have a Sapphire Lounge.
Access comes with the Chase Sapphire Reserve. The cheaper Sapphire Preferred does not include it.
The one I use most right now is the San Diego lounge. I'd rather fly out of John Wayne, since it's my home airport, but I end up at SAN when a client asks for it or the flight options are better. The lounge makes that drive a lot easier to accept.

My one rule with credit cards
I pay every card off in full, every month. No exceptions.
I get cards for two reasons: the perks, and the points that turn into free travel once they add up. Neither is worth anything if I'm paying interest. One month of carrying a balance can wipe out a year of points, and that's how it gets out of control.
So each card below has a single job. I use it for that job, I pay it off, and I collect what it gives back.
1. Chase Sapphire Reserve: my travel card
This is the one that gets me into the lounge. The annual fee is $795, which sounds crazy until you add up what comes back. That's what I mean by using it the right way.
Points:
8x on anything booked through Chase Travel
4x on flights and hotels booked directly with the airline or hotel
3x on dining
1x on everything else
Points transfer 1:1 to airline and hotel partners, which is where free flights and hotel nights come from
Perks I'd actually count:
$300 travel credit every year. It applies automatically to flights, hotels, rental cars, rideshares, even parking. If you travel at all, this brings the real cost of the card down to $495.
Sapphire Lounge and Priority Pass access with two guests
Up to $500 a year in hotel credits on stays booked through The Edit, Chase's luxury hotel collection
Up to $300 a year in dining credits at Sapphire Reserve Exclusive Tables restaurants on OpenTable
Up to $120 every four years for Global Entry or TSA PreCheck
Up to $10 a month in Lyft credits
DashPass membership plus monthly DoorDash promos
Apple TV and Apple Music subscriptions included
Primary rental car coverage, trip delay and cancellation insurance, lost luggage coverage, and no foreign transaction fees
The rental car coverage and trip insurance matter more than people think when you travel with gear and tight shoot schedules.
My honest take: if you fly a couple of times a year, this card is too expensive. If you fly every month like I do, the travel credit, the lounge, and the points cover the fee without much effort.
2. American Express Gold: points, plus my emergency fund
The Gold Card is built around food. The annual fee is $325, and like the Sapphire, it only makes sense if you use what comes with it.
Points:
4x at restaurants worldwide, on up to $50,000 a year
4x at U.S. supermarkets, on up to $25,000 a year
5x on prepaid hotels booked through Amex Travel
3x on flights booked directly with the airline or through Amex Travel
1x on everything else
Perks:
Up to $120 a year in Uber Cash, paid out as $10 a month for rides or Uber Eats
Up to $120 a year in dining credits, $10 a month at partners like Grubhub, Five Guys, and The Cheesecake Factory
Up to $100 a year at Resy restaurants, split into $50 every six months
Up to $84 a year at Dunkin', $7 a month
No foreign transaction fees
That's up to $424 a year in credits against a $325 fee. The catch is that they come in small monthly amounts, they don't roll over, and you have to enroll for most of them in the Amex app. Set them up the day you get the card.
The points are Membership Rewards. They transfer to airline and hotel partners the same way Chase points do, and having both programs gives me more options when I'm booking a trip on points.
I also use the American Express High Yield Savings Account. This is where my emergency fund lives. It has no monthly fees and no minimum balance, and it's paying around 3% APY right now. The rate moves, so check it before you open one.
I don't keep all my savings there. I keep a small portion of about three months of living expenses, I let it sit and collect interest, and I don't touch it. It's my just-in-case money.
3. SoFi Smart Card: groceries only
I use this card for groceries and nothing else, because it pays 5% back at grocery stores with no cap.
It doesn't work like a typical credit card. It's secured by my SoFi Checking and Savings balance, so I can only spend what I already have, and the balance gets paid in full every month. There's no interest and no way to carry a balance, which fits my one rule.
A few details worth knowing:
The 5% is for grocery stores and grocery delivery. Walmart, Target, and warehouse clubs like Costco don't count.
You need a SoFi Checking and Savings account and a SoFi Plus membership, which runs $10 a month. Spend more than $200 a month on groceries and the card pays for the membership.
It reports to the credit bureaus, so it still builds credit.
SoFi is also where my personal money lives. My business pays me by direct deposit into my SoFi checking, and my savings sit in their high yield savings account. I use their brokerage too, where I hold my ETFs, my Roth IRA, and my crypto. Having all of it in one app makes it easy to see where I stand.
4. Mercury IO: business only
Every business expense goes on this card. Nothing personal touches it, which keeps my books clean at tax time.
Like the SoFi card, it isn't a typical credit card. The limit is based on how much cash I have in my Mercury business account, so it's hard to overspend. The balance is paid in full automatically from that account.
1.5% cash back on every purchase, with no cap
No annual fee
No personal credit check and no personal guarantee
It builds business credit
When the cash back lands, I move it into a separate savings account inside my business account. It adds up quietly over a year of gear, travel, and production costs.
5. Apple Card: Apple purchases
I use this one to buy Apple products. I recently bought a Studio Display and a new laptop for my girlfriend on it.
3% Daily Cash on anything bought directly from Apple
3% at a few partners like Nike, Uber, and Walgreens when you pay with Apple Pay
2% on everything else paid with Apple Pay
1% when you use the physical card
No annual fee, no foreign transaction fees, no late fees
The cash back shows up the same day, which I like. Apple also lets you split Apple purchases into monthly installments at 0% interest. On a big purchase like a laptop or a display, that's the one time I'll spread a payment out, since it costs nothing extra.
6. Citi AAdvantage Platinum Select: work flights
This card comes out only when I'm booking a flight for a work trip. Every one of those flights earns AAdvantage miles, and the spend counts toward status with the airline.
2x miles on American Airlines purchases, restaurants, and gas stations
1x miles on everything else
First checked bag free on domestic American flights, for me and up to four people on my reservation
Preferred boarding
25% off food and drinks on board
A $125 American Airlines flight discount after spending $20,000 in a card year and renewing
No foreign transaction fees
$99 a year, waived the first year
The free checked bag is the perk that pays for this card. When you fly with gear, bag fees add up fast, and two round trips cover the annual fee.
Since most of my flights are for shoots, the miles stack up fast. Those miles are what pay for the trips I take for myself.
That's the whole wallet
Six cards, and each one has a single job. Travel goes on the Sapphire. Groceries go on SoFi. Business goes on Mercury. Apple goes on Apple. Work flights go on American. Everything gets paid off at the end of the month.
If you travel for work and you're still buying $40 airport breakfasts, start with the lounge. It changed how I use my travel days more than any other perk I have.
If you liked this, I can go deeper on how I manage my accounts, especially on the business side. I have everything automated for taxes and expenses, and I pay myself a monthly wage with a real pay stub. Let me know and I'll write that one next.
This is what works for me and my business. It isn't financial advice, and card terms change, so check the current details before you apply for anything.
Sources
Share this article
Article
/
My Office Is Waiting at the Gate (Thanks, Chase Sapphire)
My Office Is Waiting at the Gate (Thanks, Chase Sapphire)
My Office Is Waiting at the Gate (Thanks, Chase Sapphire)
My Office Is Waiting at the Gate (Thanks, Chase Sapphire)
My Office Is Waiting at the Gate (Thanks, Chase Sapphire)
Words by
Oveth Martinez
Published on
10.12.2026
For years I spent that time the way most people do. I'd hunt for an outlet, sit on the floor next to it, and pay airport prices for a coffee and a sad breakfast sandwich. Then I got a card that gets me into the Chase Sapphire Lounge, and that dead time turned into some of my most productive hours while I wait for my flight.
Not many people talk about this, at least not photographers, so here's what I use. I'll start with the lounge, then walk through the six cards I carry and the one job each of them has.
Why the lounge is the best office in the airport
The Sapphire Lounge gives me a real seat, fast Wi-Fi, outlets, and enough quiet to actually think. That's all I need to get work done before a flight.
I use that window to answer client emails, send invoices, cull selects from the last shoot, and go over the shot list for the one I'm flying to. By the time I board, my inbox is handled and I can sleep on the plane without feeling behind.
Then there's the food. Coffee, a proper breakfast, and drinks are all included. At the terminal, a coffee and a basic airport breakfast runs me $30, $40, sometimes $50. Do that on both legs of a trip and you've spent close to $100 before the job has even started. In the lounge it costs nothing extra.
A few things to know before you plan around it:
Sapphire Lounges are open in Boston, Las Vegas, New York (LaGuardia and JFK), Philadelphia, Phoenix, and San Diego. Dallas/Fort Worth and Los Angeles are planned.
You can bring two guests in for free.
The same card comes with a Priority Pass Select membership, which covers 1,300+ other lounges around the world for the airports that don't have a Sapphire Lounge.
Access comes with the Chase Sapphire Reserve. The cheaper Sapphire Preferred does not include it.
The one I use most right now is the San Diego lounge. I'd rather fly out of John Wayne, since it's my home airport, but I end up at SAN when a client asks for it or the flight options are better. The lounge makes that drive a lot easier to accept.
My one rule with credit cards
I pay every card off in full, every month. No exceptions.
I get cards for two reasons: the perks, and the points that turn into free travel once they add up. Neither is worth anything if I'm paying interest. One month of carrying a balance can wipe out a year of points, and that's how it gets out of control.
So each card below has a single job. I use it for that job, I pay it off, and I collect what it gives back.
1. Chase Sapphire Reserve: my travel card
This is the one that gets me into the lounge. The annual fee is $795, which sounds crazy until you add up what comes back. That's what I mean by using it the right way.
Points:
8x on anything booked through Chase Travel
4x on flights and hotels booked directly with the airline or hotel
3x on dining
1x on everything else
Points transfer 1:1 to airline and hotel partners, which is where free flights and hotel nights come from
Perks I'd actually count:
$300 travel credit every year. It applies automatically to flights, hotels, rental cars, rideshares, even parking. If you travel at all, this brings the real cost of the card down to $495.
Sapphire Lounge and Priority Pass access with two guests
Up to $500 a year in hotel credits on stays booked through The Edit, Chase's luxury hotel collection
Up to $300 a year in dining credits at Sapphire Reserve Exclusive Tables restaurants on OpenTable
Up to $120 every four years for Global Entry or TSA PreCheck
Up to $10 a month in Lyft credits
DashPass membership plus monthly DoorDash promos
Apple TV and Apple Music subscriptions included
Primary rental car coverage, trip delay and cancellation insurance, lost luggage coverage, and no foreign transaction fees
The rental car coverage and trip insurance matter more than people think when you travel with gear and tight shoot schedules.
My honest take: if you fly a couple of times a year, this card is too expensive. If you fly every month like I do, the travel credit, the lounge, and the points cover the fee without much effort.
2. American Express Gold: points, plus my emergency fund
The Gold Card is built around food. The annual fee is $325, and like the Sapphire, it only makes sense if you use what comes with it.
Points:
4x at restaurants worldwide, on up to $50,000 a year
4x at U.S. supermarkets, on up to $25,000 a year
5x on prepaid hotels booked through Amex Travel
3x on flights booked directly with the airline or through Amex Travel
1x on everything else
Perks:
Up to $120 a year in Uber Cash, paid out as $10 a month for rides or Uber Eats
Up to $120 a year in dining credits, $10 a month at partners like Grubhub, Five Guys, and The Cheesecake Factory
Up to $100 a year at Resy restaurants, split into $50 every six months
Up to $84 a year at Dunkin', $7 a month
No foreign transaction fees
That's up to $424 a year in credits against a $325 fee. The catch is that they come in small monthly amounts, they don't roll over, and you have to enroll for most of them in the Amex app. Set them up the day you get the card.
The points are Membership Rewards. They transfer to airline and hotel partners the same way Chase points do, and having both programs gives me more options when I'm booking a trip on points.
I also use the American Express High Yield Savings Account. This is where my emergency fund lives. It has no monthly fees and no minimum balance, and it's paying around 3% APY right now. The rate moves, so check it before you open one.
I don't keep all my savings there. I keep a small portion of about three months of living expenses, I let it sit and collect interest, and I don't touch it. It's my just-in-case money.
3. SoFi Smart Card: groceries only
I use this card for groceries and nothing else, because it pays 5% back at grocery stores with no cap.
It doesn't work like a typical credit card. It's secured by my SoFi Checking and Savings balance, so I can only spend what I already have, and the balance gets paid in full every month. There's no interest and no way to carry a balance, which fits my one rule.
A few details worth knowing:
The 5% is for grocery stores and grocery delivery. Walmart, Target, and warehouse clubs like Costco don't count.
You need a SoFi Checking and Savings account and a SoFi Plus membership, which runs $10 a month. Spend more than $200 a month on groceries and the card pays for the membership.
It reports to the credit bureaus, so it still builds credit.
SoFi is also where my personal money lives. My business pays me by direct deposit into my SoFi checking, and my savings sit in their high yield savings account. I use their brokerage too, where I hold my ETFs, my Roth IRA, and my crypto. Having all of it in one app makes it easy to see where I stand.
4. Mercury IO: business only
Every business expense goes on this card. Nothing personal touches it, which keeps my books clean at tax time.
Like the SoFi card, it isn't a typical credit card. The limit is based on how much cash I have in my Mercury business account, so it's hard to overspend. The balance is paid in full automatically from that account.
1.5% cash back on every purchase, with no cap
No annual fee
No personal credit check and no personal guarantee
It builds business credit
When the cash back lands, I move it into a separate savings account inside my business account. It adds up quietly over a year of gear, travel, and production costs.
5. Apple Card: Apple purchases
I use this one to buy Apple products. I recently bought a Studio Display and a new laptop for my girlfriend on it.
3% Daily Cash on anything bought directly from Apple
3% at a few partners like Nike, Uber, and Walgreens when you pay with Apple Pay
2% on everything else paid with Apple Pay
1% when you use the physical card
No annual fee, no foreign transaction fees, no late fees
The cash back shows up the same day, which I like. Apple also lets you split Apple purchases into monthly installments at 0% interest. On a big purchase like a laptop or a display, that's the one time I'll spread a payment out, since it costs nothing extra.
6. Citi AAdvantage Platinum Select: work flights
This card comes out only when I'm booking a flight for a work trip. Every one of those flights earns AAdvantage miles, and the spend counts toward status with the airline.
2x miles on American Airlines purchases, restaurants, and gas stations
1x miles on everything else
First checked bag free on domestic American flights, for me and up to four people on my reservation
Preferred boarding
25% off food and drinks on board
A $125 American Airlines flight discount after spending $20,000 in a card year and renewing
No foreign transaction fees
$99 a year, waived the first year
The free checked bag is the perk that pays for this card. When you fly with gear, bag fees add up fast, and two round trips cover the annual fee.
Since most of my flights are for shoots, the miles stack up fast. Those miles are what pay for the trips I take for myself.
That's the whole wallet
Six cards, and each one has a single job. Travel goes on the Sapphire. Groceries go on SoFi. Business goes on Mercury. Apple goes on Apple. Work flights go on American. Everything gets paid off at the end of the month.
If you travel for work and you're still buying $40 airport breakfasts, start with the lounge. It changed how I use my travel days more than any other perk I have.
If you liked this, I can go deeper on how I manage my accounts, especially on the business side. I have everything automated for taxes and expenses, and I pay myself a monthly wage with a real pay stub. Let me know and I'll write that one next.
This is what works for me and my business. It isn't financial advice, and card terms change, so check the current details before you apply for anything.
Sources
Share this article